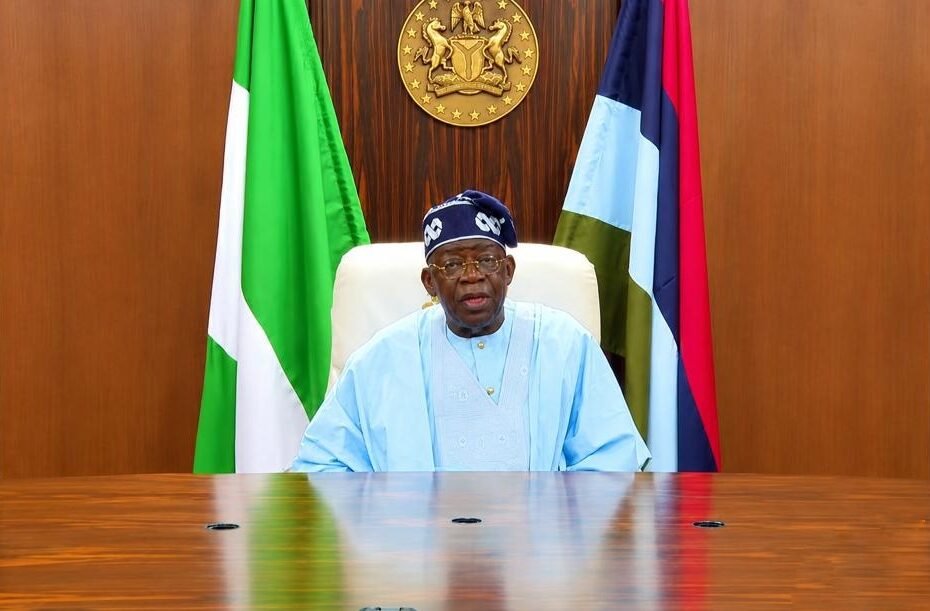
According to the Debt Management Office (DMO), Nigeria’s public debt stood at ₦166.79 trillion as of June 2026, representing an increase of ₦79.41 trillion in approximately three years.
 By Abba Dukawa
·
Published on November 8, 2026
·
7 min read
When President Bola Ahmed Tinubu assumed office on May 29, 2023, Nigeria was already facing substantial public debt, rising inflation, foreign exchange instability, and mounting economic challenges. He promised economic renewal and a departure from the failures of the past. However, three years into his administration, the country’s growing debt profile raises serious questions about the sustainability of its economic direction.
According to the Debt Management Office (DMO), Nigeria’s public debt stood at ₦166.79 trillion as of June 2026, representing an increase of ₦79.41 trillion in approximately three years. This exceeds the ₦75.26 trillion increase recorded during former President Muhammadu Buhari’s eight-year administration, including the controversial ₦23 trillion Ways and Means advances.
The figures raise an important question: Is Nigeria borrowing to build prosperity or simply postponing difficult economic decisions?
2023: The Beginning of Accelerated Borrowing
Borrowing increased shortly after Tinubu assumed office. In June 2023, the World Bank approved $750 million for the Power Sector Recovery Programme, $500 million for the Nigeria for Women Programme Scale-Up, and $800 million for the National Social Safety Net Programme Scale-Up.
These facilities were intended to support economic reforms, improve electricity supply, and cushion vulnerable households against the consequences of fuel subsidy removal. However, questions persist about beneficiary selection, transparency, and the measurable impact of social intervention programmes.
In August 2023, Nigeria secured a reported $3 billion financing facility from Afreximbank, linked to future crude oil revenues. Another $700 million was approved in September for the Adolescent Girls Initiative for Learning and Empowerment, while December brought $750 million for the Distributed Access through Renewable Energy Scale-up programme.
Meanwhile, approximately ₦22.7 trillion in accumulated Ways and Means advances was securitised in December 2023, converting previously accumulated Central Bank financing into formal debt obligations.
The government also raised substantial domestic financing through FGN bonds and Treasury bills. Consequently, public debt rose sharply, although changes in exchange rates and the recognition of previously accumulated liabilities must also be considered when assessing the increase.
2024: Borrowing Under Development Programmes
The borrowing trend continued in 2024. In March, the government launched the Lagos–Calabar Coastal Highway project, estimated at approximately $11 billion. The project attracted controversy over procurement transparency, competitive bidding, and environmental concerns.
On June 13, the World Bank approved $1.5 billion for the Reforms for Economic Stabilization to Enable Transformation (RESET) programme and $750 million for Accelerating Resource Mobilization Reforms (ARMOR).
In July, the African Development Bank approved another $500 million to support economic governance and energy transition reforms.
September brought a further financing package reportedly totalling $1.57 billion, covering HOPE-GOV, HOPE-PHC, and Sustainable Power and Irrigation for Nigeria (SPIN).
In December 2024, Nigeria issued a $2.2 billion Eurobond to finance its budget deficit. The reported yields exceeded 9%, highlighting the expensive nature of accessing international capital markets.
By the end of 2024, public debt reportedly stood at ₦144.67 trillion. These developments raise concerns about the growing cost of borrowing and whether the projects financed are delivering sufficient economic returns.
2025: Borrowing Becomes Entrenched
On March 31, 2025, another $1.08 billion in financing was reported for NG-CARES, HOPE-EDU and ANRIN 2.0, covering economic recovery, education, and nutrition.
In May, the government raised approximately ₦1.39 trillion through its seventh FGN Sukuk issuance to finance road infrastructure.
In July, the Federal Government presented an external borrowing plan covering 2025 and 2026, comprising $21.5 billion, €65 million, and ¥15 billion. The National Assembly subsequently approved the plan.
By December 2025, Nigeria’s public debt was reportedly ₦159.28 trillion, while debt servicing stood at ₦15.81 trillion. This figure highlights the growing pressure on government finances and the resources available for healthcare, education, infrastructure, and security.
2026: A Growing Debt Burden
In March 2026, the Senate reportedly approved a fresh $6 billion external borrowing request, including a controversial $5 billion financing arrangement involving First Abu Dhabi Bank. An initial $1.5 billion tranche was reportedly drawn in June.
The government also reportedly secured $1 billion through UK Export Finance for the rehabilitation of Lagos Port Complex and Tin Can Island Port. Given the existing concession arrangements at these ports, Nigerians deserve clarification about the respective financial responsibilities of government and private operators.
By June 2026, the DMO reported total public debt of ₦166.79 trillion, comprising ₦91.59 trillion in domestic debt and ₦75.2 trillion in external debt.
In September, discussions reportedly began on another $1.5 billion World Bank financing package covering climate resilience, household prosperity, and early childhood development.
In October, another borrowing controversy emerged. Following an earlier proposal involving $20.52 billion and €1.045 billion, a revised borrowing plan of $7.7 billion, reportedly equivalent to ₦10.58 trillion, was presented.
Why does Nigeria continue seeking fresh loans despite repeated assurances of increasing government revenue and economic recovery? Borrowing should not become routine administrative business without adequate public scrutiny.
What Does Rising Debt Mean for Nigerians?
Four major concerns deserve attention:
- The burden on future generations
With an estimated population of 230 million and public debt of ₦173.4 trillion, the implied debt per capita is approximately ₦754,043. This is not an individual legal repayment obligation, but it illustrates the scale of national liabilities that future taxpayers may inherit.
- The debt-servicing trap
The reported ₦15.81 trillion spent on debt servicing in 2025 raises questions about Nigeria’s fiscal priorities. Compared with reported allocations of ₦3.2 trillion for education, ₦2.4 trillion for health, and ₦4.9 trillion for defence, debt servicing represents a substantial competing demand on public resources.
The government must demonstrate that it can meet repayment obligations without sacrificing essential public services.
- Infrastructure without sufficient accountability
Nigerians deserve evidence of what billions of dollars in loans have achieved. Funding for education, healthcare, electricity, and social protection should be assessed through measurable improvements, not merely announcements and project titles.
Which projects have been completed? How many communities have benefited? What independent evaluations establish value for money?
Borrowing is justified when it produces sustainable economic benefits. Without transparent project-level reporting, citizens cannot determine whether the cost of these loans is worthwhile.
- Future oil revenues and financial commitments
The reported Afreximbank and First Abu Dhabi Bank arrangements raise concerns about possible commitments involving future government revenues. Such financing can provide immediate liquidity but may restrict future fiscal flexibility.
The government must disclose the contractual terms, repayment schedules, collateral arrangements, and total financial costs. A loan secured against oil revenues should not automatically be described as an outright sale of future crude oil production.
Nigeria’s Borrowed Future
Supporters of Tinubu’s economic policies argue that borrowing is necessary to finance reforms and infrastructure. They also point to Nigeria’s relatively moderate debt-to-GDP ratio.
However, debt sustainability cannot be determined by GDP comparisons alone. Government revenue, interest rates, currency exposure, repayment schedules, and returns on borrowed funds are equally important.
A country may have a manageable debt-to-GDP ratio yet face serious fiscal difficulties when a substantial proportion of its revenue goes towards debt servicing.
The administration must therefore explain why borrowing continues despite the removal of fuel subsidies, increased revenue allocations to states, and reported improvements in tax mobilisation.
The National Assembly must strengthen legislative oversight, while the DMO and Ministry of Finance should publish accessible information on loan agreements, disbursements, repayment obligations, and project outcomes.
Nigeria does not necessarily have a borrowing problem simply because it takes loans. It has a potential accountability and sustainability problem if borrowing increases without corresponding improvements in citizens’ welfare and productive capacity.
Renewed Hope should translate into affordable living, employment opportunities, reliable infrastructure, quality education, and accessible healthcare. It should not leave future generations with mounting liabilities and fewer economic choices.
Ultimately, leadership must be measured not by the volume of money borrowed but by the prosperity created with it.
If Renewed Hope is the promise, why are hardship and rising debt becoming the reality? Nigeria deserves answers, transparency, and responsible leadership.
